A commercial loan calculator estimates your monthly payment from three inputs: the amount borrowed, the interest rate or cost, and the repayment term. Bank and SBA loans quote an annual rate, so total interest is easy to compare across offers. Short-term products quote a factor rate, which has to be converted to an APR-equivalent before it can be set beside a bank loan.
What a Commercial Loan Calculator Measures #
A commercial loan calculator answers a practical question before you apply: what will this money cost each month, and what will it cost in total? It works like the mortgage or auto loan calculators you may already have used. You enter the amount, the rate and the term, and it returns a payment and a total.
It does not tell you whether you will be approved, what rate a lender will offer, or whether your cash flow can carry the payment. Those depend on your credit, time in business, revenue and collateral. A calculator gives you a number to test against your own books, not a quote.
Many owners use it as a first filter. If the payment would squeeze payroll or rent, the loan is the wrong size or the wrong product. You learn that in minutes, not after an application.
Inputs You Need Before You Run the Numbers #
Four inputs do most of the work.
- Amount borrowed. Enter the full amount you will borrow. Note any fee deducted from the proceeds, because you pay on the full amount but receive less.
- Rate or cost. For a bank or SBA loan this is an annual interest rate. For a short-term product it is a factor rate, which must be converted before you compare it with anything. For example, a 1.25 factor over eight months is roughly 63% APR-equivalent.
- Term. The number of months or years you will repay. A longer term lowers the payment and raises total interest.
- Payment frequency. Monthly, weekly or daily. Daily and weekly payments change how much cash you need on hand, even when the total is the same.
Also gather any origination fee, closing cost or prepayment term. A calculator only prices what you tell it.
Reading the Output: Payment, Total Cost and Effective Rate #
Most calculators return three figures. The first is the periodic payment. The second is total repaid, which is the payment times the number of payments. The third is total cost, the total repaid minus the amount borrowed.
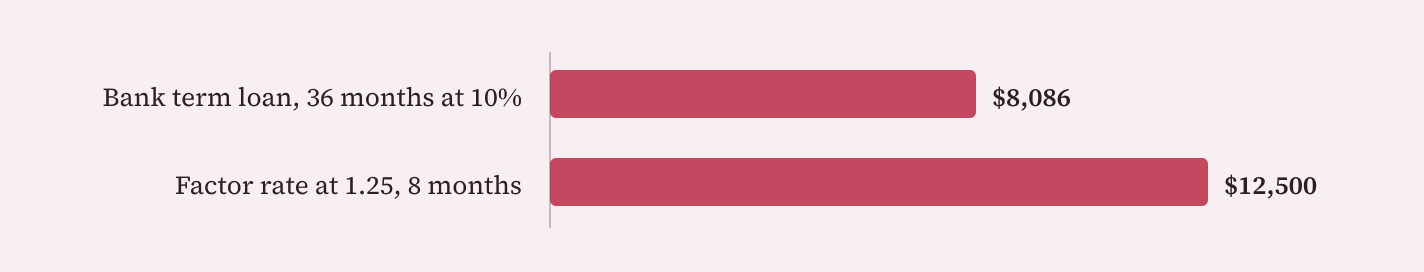
Take a worked example. For example, $50,000 at a 10% annual rate over 36 months has a monthly payment of about $1,614. Over the full term you repay about $58,086, so the interest cost is about $8,086. This is a fully amortizing loan: each payment covers interest first and then reduces the balance, which reaches zero at month 36.
The effective rate is the number to compare across products. A stated rate can understate the real cost once fees are added, and a payment schedule can hide the true annual cost. When you compare two offers, compare total dollars and the APR-equivalent, using the same amount and term wherever possible.
Converting Factor Rates to APR-Equivalents #
A factor rate is a multiplier. You take the amount funded and multiply it by the factor to get the total repaid. A 1.25 factor on $50,000 means $62,500 repaid, a $12,500 finance charge, or roughly 63% APR over eight months. The factor does not change with time, so it does not look like an interest rate, and it cannot be set directly beside a 10% bank rate.
To convert it, you need the term and the payment schedule. Start with the finance charge divided by the amount funded: $12,500 ÷ $50,000 = 25%. That 25% is the cost for eight months. Annualizing it simply (25% × 12 ÷ 8) gives 37.5%, which understates the cost, because you do not keep the full $50,000 for the whole period. You repay it in pieces.
A closer method treats the repayment like a loan. Divide the $62,500 into eight equal monthly payments of about $7,813, then solve for the rate that brings the $50,000 to the present value of those payments. That lands near 5.2% a month, or roughly 63% APR on a nominal annual basis.
The result moves with the schedule. Daily remittances taken from card sales, a fee deducted up front, or a shorter term each push the APR-equivalent higher. Ask the provider for the annualized rate in writing. California and New York both require standardized disclosures for many commercial financings, including an annualized rate, so the number should be available before you sign.
Comparing Bank Term Loans, SBA 7(a) and Short-Term Funding #
Each option trades cost against speed and paperwork. The table sets them side by side. The costs describe how each product is priced, not a quote, because your offer depends on your file.
| Option | Typical cost | Speed | What it needs |
|---|---|---|---|
| Bank term loan | Annual interest rate set by the bank and your credit; for example 10% in the worked example above | Often several weeks | How long you have operated, your financial statements and tax returns, and at times assets pledged as security |
| The SBA 7(a) loan | Annual rate set by the lender within SBA limits, plus a guaranty fee in some cases | Often several weeks to months | SBA eligibility, a business plan, financials, usually a personal guarantee |
| Credit lines for businesses | Interest only on the drawn balance, often variable, plus any draw or maintenance fees | Days to weeks to open; draws are quick once it is in place | Credit history and revenue; collateral or a guarantee for some |
| Merchant cash advance | Factor rate; for example 1.25 ≈ 63% APR over eight months | Often within days | Recent card sales or deposits and several months of bank statements |
| Short-term business loan | Factor rate or fixed fee; convert it to an APR-equivalent before comparing | Often within days | Recent revenue and bank statements |
Bank term loans and The SBA 7(a) loans usually carry the lowest annual rates of these options, and they fund the slowest. Lines of credit suit a cash gap you can see coming. Short-term products fund fastest and cost the most per dollar. The sba 7a loan requirements page walks through eligibility, credit and collateral for the SBA program.
The Federal Reserve's Small Business Credit Survey tracks how often small firms apply for each type of financing and how often they are approved. That is a useful reminder that approval is never guaranteed, whichever product you choose.
Frequently Asked Questions #
How do I calculate the monthly payment on a commercial loan? #
Use the standard amortization formula. Divide the annual rate by 12 to get the monthly rate. Then multiply the amount borrowed by that rate and divide by one minus (one plus the monthly rate) raised to the negative number of payments. For $50,000 at 10% over 36 months, the monthly rate is about 0.83% and the payment is about $1,614. A calculator does this for you; the formula helps you check its output. Use the annual rate only for bank and SBA loans. For factor-rate products, convert first.
What is the difference between an interest rate and a factor rate? #
An interest rate is a yearly percentage charged on the balance you still owe, so the cost falls as you repay. A factor rate is a fixed multiplier applied to the amount funded, so the total cost is set on the first day. A 1.25 factor on $50,000 means $12,500 in cost, roughly 63% APR over eight months. Read the prepayment terms, because they decide whether paying early saves you anything.
How do I convert a factor rate to an APR-equivalent? #
First find the finance charge: amount funded times the factor, minus the amount funded. Divide that by the amount funded to get the total percent cost. Then, using the payment amount and number of payments, solve for the rate that equates the funded amount with the present value of the payments. For the 1.25 example over eight equal monthly payments, that is about 5.2% a month, or roughly 63% APR nominal. A simple annualization is faster but gives a lower number. Use the annualized rate from the provider's disclosure when one is given.
Does a commercial loan calculator include fees and origination costs? #
Usually not. Most calculators price the payment schedule on the amount you enter, so origination fees, closing costs, broker fees and prepayment charges are left out unless you add them. A fee deducted from the proceeds means you receive less than the amount you pay interest on, so the real cost is higher than the calculator shows. Add the fee to the total cost by hand, or ask the provider for an all-in annualized rate.
Is a lower monthly payment always the cheaper loan? #
No. A lower payment usually comes from a longer term, and a longer term raises total interest. For example, stretching the $50,000 at 10% from 36 months to 60 months lowers the payment to about $1,062 a month but adds roughly $13,700 in total interest, compared with about $8,086 at 36 months. A lower payment can help cash flow, so it has a real purpose. Judge the loan on total cost and on whether the payment fits your margin.
Matching the Money to the Job #
A bank term loan or The SBA 7(a) loan is usually the right tool when the money buys something with a long working life, such as equipment or a build-out, or when you need working capital you can plan for. You will wait longer and submit more paperwork, but the lower annual rate rewards that patience. Before you apply, check whether your cash flow supports the payment with a debt service coverage ratio calculator.
A line of credit fits a gap you can predict, such as seasonal inventory or the timing of payroll against collections. You pay interest only on what you draw.
Short-term funding fits an urgent, short need tied to revenue that is coming: a bridge to a known receivable or an unexpected repair. It is the costliest option here. At roughly 63% APR-equivalent, every month you carry it adds up. If a bank or SBA lender can fund on your timeline, that is usually the cheaper path. If receivables would be the collateral, compare accounts receivable financing vs factoring before deciding.
It is not the right fit for a loan you cannot repay from cash flow in the first few months, for money with no clear return, or for any offer whose cost you cannot see as an APR-equivalent in writing.
If the numbers hold up in the calculator and your cash flow covers the payment with room to spare, start your request through our network of funding partners.
Sources #
This explainer offers general information and is not advice tailored to your situation. Only the terms written into an agreement you sign apply to you. How this site is paid.